• Home
  • Economy
  • The Term Spread As Recession Predictor, Post-2024
Image

The Term Spread As Recession Predictor, Post-2024


Using a plain vanilla term spread model (spread, short rate), what remains? From notes for tomorrow’s lecture.
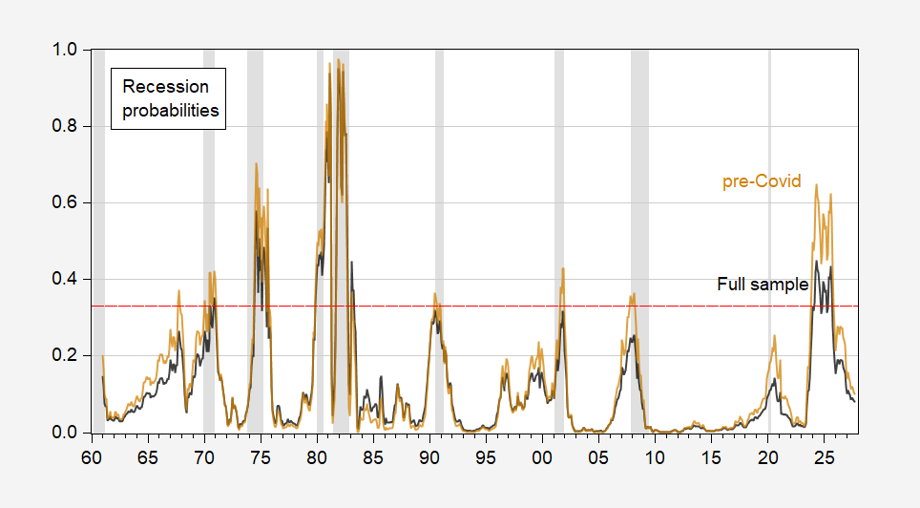
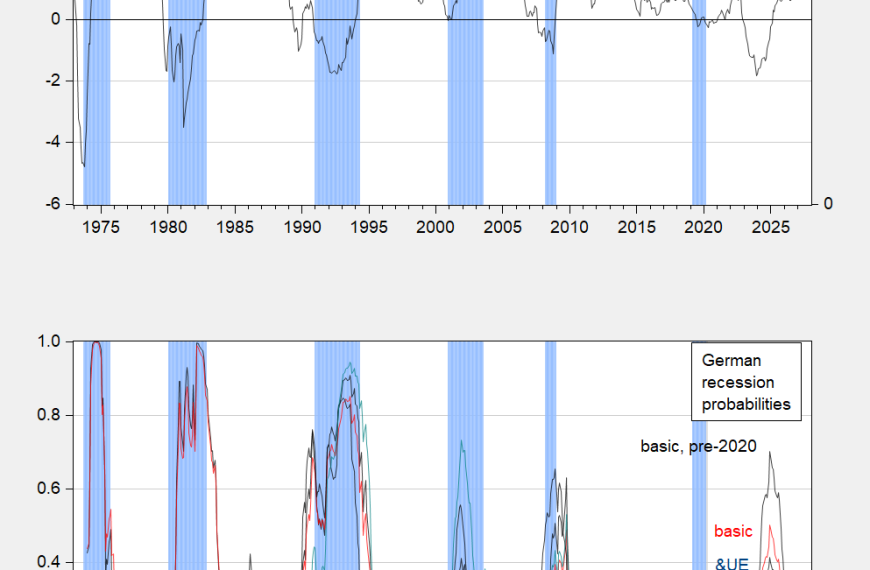
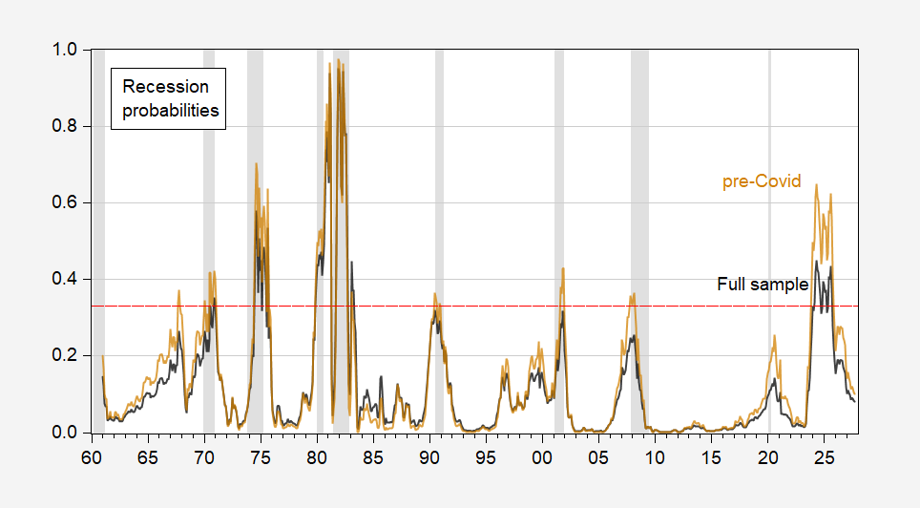
Figure 1: Estimated recession probabilities from probit on 10yr-3mo term spread, short rate over 1960-2018 (brown), over full sample (black). Red dashed line at 33%. NBER defined peak-to-trough recession dates shaded gray. Source: author’s calculations, NBER.

Using a 33% threshold and the pre-2018 sample, the term spread catches every post-1960 recession (taking the pandemic recession was not a typical recession), but gives the false positive for 2024. The full sample regression (assumes no recession appears by 2026M08) no longer catches the 1990-91, 2001, and 2007-09 recessions, and still provides a false positive for 2024.

In other respects, the full sample regression is less successful; the pseudo-R2 drops from 0.30 to 0.25.

This entry was posted on by Menzie Chinn.


Source link

Releated Posts

Understanding Economics: Capital Isn’t Capitalism

Yves here. Confucius said that the beginning of wisdom is calling things by their proper names. So the…

ByByNews on SantoshHub Nov 14, 2026

Why the Microsoft 365 Outage Is Different and Why It Takes So Long to Restore Email Services

Yves here. Since many readers are tech-knowledgeable, I hope this post o Microsoft 360 falling over will stimulate…

ByByNews on SantoshHub Nov 14, 2026

Links 11/14/2026

This magic mushroom can kill ScienceNews Across the U.S., homegrown experiments aim to save kids from their phones…

ByByNews on SantoshHub Nov 14, 2026

What Did the German Term Spread Predict for 2024?

The 10yr-3mo German spread, hitherto a pretty good predictor, inverted at 2022M12. Hitherto a pretty good predictor of…

ByByNews on SantoshHub Nov 14, 2026

Leave a Reply

Your email address will not be published. Required fields are marked *

Scroll to Top