

Yves here. Das provides a sober look at the hype and reality of gold ownership.
By Satyajit Das, a former banker and author of numerous technical works on derivatives and several general titles: Traders, Guns & Money: Knowns and Unknowns in the Dazzling World of Derivatives (2006 and 2010), Extreme Money: The Masters of the Universe and the Cult of Risk (2011) and A Banquet of Consequences (2016 and 2021). His latest book, The Everything Bubble: A Guide to the New Age of Financial Speculation and Phantom Wealth,> will be released in 2027. He has also written on ecotourism – In Search of the Pangolin (2006) (with Jade Novakovic) and Wild Quests: Journeys into Ecotourism and the Future for Animals (2024). This piece was first published by New Indian Express
Recent fluctuations in the gold price resemble a carnival thrill ride. From 2018, particularly after 2022, it increased reaching a peak of around $5,300 in early 2026. It then fell and is currently trading around $4,000. Over the last decade, even after recent falls, gold has risen around 300 percent.
The initial momentum came from the debasement trade. Rising price pressures in the aftermath of the Covid19 pandemic and Ukraine war created concern about the purchasing power of paper money. This was exacerbated by the decision of the US and its allies to weaponize finance through sanctions, trade restrictions, seizure of Russian foreign exchange reserves and overseas assets, and denying access to payment systems. In combination with erratic American policies around the devaluation of the dollar and restructuring of Treasury bonds, this encouraged a switch to hard assets, such as gold.
Investors and especially central banks increased their holdings of the precious metal. Central banks purchased an average of 1,000 tonnes a year over the past four years, double the average of the previous decade, taking their total holding to more than 36,000 tonnes. Fear of confiscation has meant that gold at 27 percent is now larger than central bank holdings of US government bonds (22 percent).
Only around 220,000 metric tons of gold have been mined through history, equivalent to a single 22.3 metre solid cube. The stock grows by 3,000–3,700 tons, 1.5–2 percent, annually. There have been few major discoveries in recent years because of lower exploration spending, in part due to unattractive prices and most miners favouring more economic copper-gold orebodies. This meant that the sudden demand shock drove prices sharply higher.
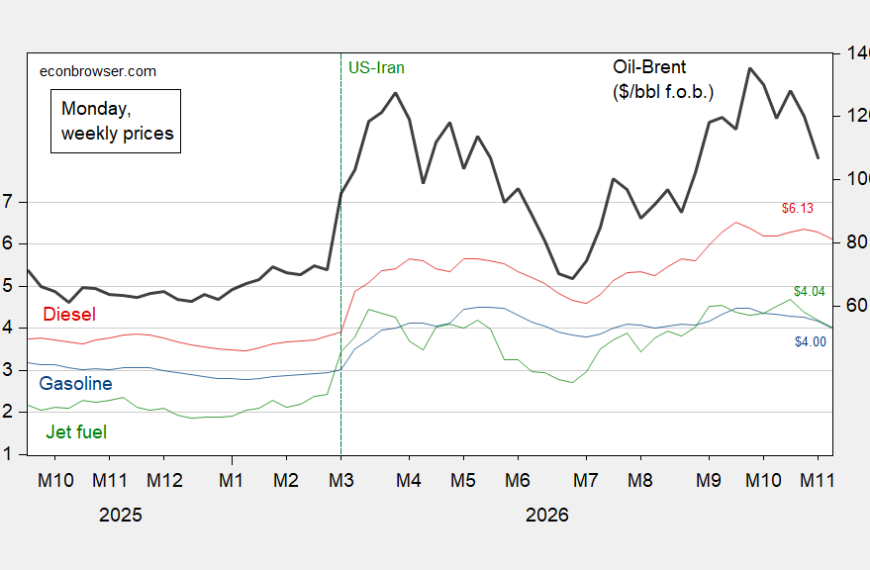
The retracement is surprising given that the pressures identified remain intact. It may have been driven by fear of rising interest rates, and a recovery in the dollar after the launch of US-Israeli attacks on Iran. Uncertainty about the Federal Reserve policies under new Chair Kevin Warsh, which is raising interest rates, was another factor. As gold pays no income, higher interest rates increase the opportunity or holding cost. As it is quoted in dollars, currency movements inversely affect the metal’s price.
The fall may have also resulted from liquidation of gold holdings, in the wake of Operation Epic Fury, to meet cash needs or cover margins calls amidst volatile markets. Central banks in India, Indonesia and Turkey sold gold reserves to support their embattled currencies as capital fled emerging markets. It may also have been profit taking after the sharp price increase or rebalancing of portfolios with fast money switching to bets on AI, memory chips, semi-conductors, and other technology investments.
Gold defies logical explanation. Warren Buffett was a sceptic: “Gold gets dug out of the ground … we melt it down, dig another hole, bury it again, and pay people to stand around guarding it.” Industrial use (45 percent culturally based jewellery demand, mainly from India and China, and 15 percent industrial applications primarily in electronics) follows some economic logic. The remaining 40 percent, primarily to meet investment demand, is mired in tenuous theories.
The investment case is mixed. Its tactical value over specific periods is significant. But gold is not itself a great store of value, at least over long time periods. While it reached its highest real (inflation adjusted) price in early 2026, at around $4,000 it is barely above the 1980 price meaning that investors have earned nothing or very little over nearly half a century. Dylan Grice of Société Générale summed up its performance: “A 15th century gold bug who’d stored all his wealth in bullion, bequeathed it to his children and required them to do the same would be more than a little miffed when gazing down from his celestial place of rest to see the real wealth of his lineage decline by nearly 90 per cent over the next 500 years.”
Gold is supposed to offer a safe haven in crises. Yet, in 2026, the gold price actually fell during geopolitical turmoil. Its safe haven role, at least relative to equities, seems to vary by sector and is affected by interest rates and cyclic trends. One reason for this is the financialisaton of gold investment where investors hold paper gold primarily through funds or derivative instruments which are affected by other risks, such as margin calls, counterparty, typically bank, and liquidity risk. Even with physical gold, there is exposure to the custodian. At best, gold absorbs some of the volatility but does not guarantee security.
Adding gold to investor portfolios theoretically increases diversification and stability. This assumes a negative correlation between equities and gold. In recent times, this relationship has become unstable with both moving in the same direction at times. It can also be volatile adversely affecting investment performance.
While many draw distinctions, gold and fiat or paper money are similar. They both are valueless in themselves because they cannot be directly consumed and must be converted into needed real goods or services. That relies on acceptance as a medium of exchange, which in turn relies on trust.
Current developments in gold point to a deepening anxiety about the world’s economic trajectory. There is disquiet about debt that can never be repaid, endless budget deficits, lax monetary policies, rampant speculation, and public funded bailouts. Sensible people decry the fundamental short-term approach and lack of will to address the primary issues of the times. They sense that governments, policymakers and elites will seek to prop up the system and preserve their positions and wealth through wars and by inflating away unsustainable debt. People want a return to a place where currencies are stable and retain their purchasing power but fear the hyper-inflationary nightmare of Weimar and the failure of money. As one a banker asked an old German woman seeking to redeem her worthless investments: “where is the State which guaranteed these securities to you? It is dead.”
With the problems seemingly unsolvable and with most major currencies infected by the same issues, gold now functions as little more than an alternative currency. It is the least dirty shirt in the laundry basket. Ordinary people place their faith in its tangible nature and storied history because they have no other choice.
© 2026 Satyajit Das All Rights Reserved


 By