
Silicon Valley is down with POTUS Trump’s rebranding of “artificial intelligence” as “super intelligence” but that hasn’t freed the “super intelligence” companies of their need for massive capital infusions.
SI, Yes AI, No
First the rebranding via The Verge:
When President Donald Trump announced his plans to rebrand artificial intelligence as “super intelligence,” you’d be forgiven for being skeptical that it would catch on. While most of the broader population is sticking with AI, some of Silicon Valley’s most powerful are falling in line and trying to give Trump the great AI rebrand he so desires.
That Elon Musk was quick to jump on board, promising to rename SpaceXAI to SpaceXSI, isn’t surprising. When, hours after Donald Trump declared that “The White House considers anyone that uses the term, ‘Artificial Intelligence,’ as opposed to the highly accepted new and more accurate term, ‘Super Intelligence,’ THE ENEMY!” Marc Benioff announced that Salesforce would rename AIForce to SIForce; it seemed like a quick capitulation, but not entirely out of character.
Nvidia CEO Jensen Huang attended the summit where the executive order requiring government agencies to use the term “super intelligence” was announced. He’s also aligned himself with Trump, saying he believes the danger posed by AI is overblown. So it was somewhat predictable that when Nvidia declared that it would “commit” $1 billion to scientific advancement, that included “super intelligence research.” Of course, Huang has a lot to lose if he gets on Trump’s bad side.
The latest to cave is Microsoft’s Satya Nadella, who attended the same AI summit as Huang along with Mark Zuckerberg, Sundar Pichai, Jeff Bezos, Dario Amodei, and Musk. In a post calling for building an “emergency brake” for AI yesterday, Nadella repeatedly referred to the technology as “super intelligence.”
As much as you’d think this name change would be revolutionary, it doesn’t appear to have impacted balance sheets.
Capital Is the Tech Bottleneck
Tech titans gathered at the DBS Asia Future Forward Conference in Singapore on Monday and the consensus was clear: capital not hardware is the biggest bottleneck facing the industry.
CNBC reported:
Broadcom CEO Hock Tan said financing could become a bigger obstacle to AI expansion than shortages of semiconductors, memory chips or electricity, as the industry races to build the infrastructure needed to power increasingly sophisticated models.
″[What] I think might be the biggest constraint is capital,” Hock Tan said at the DBS Asia Future Forward Conference in Singapore on Monday.
Intel CEO Lip-Bu Tan echoed concerns about financing, pointing to the rising cost of capital and questions over whether companies investing heavily in AI will eventually generate sufficient returns.
“If there’s any challenge in the front, it’s capital and the cost of capital, and then the other part is in the longer run, people want to see the ROI,” he said.
Their remarks highlight an emerging challenge for the AI industry, which has poured enormous sums into data centers, advanced chips and power infrastructure in anticipation of surging demand for computing capacity.
The warnings come as rising borrowing costs threaten to complicate financing for technology companies investing heavily in AI infrastructure. Higher bond yields could make it more expensive to fund data center construction and chip purchases, potentially putting pressure on the economics of projects that may take years to generate returns.
How much debt are we talking about? This much debt:
AI debt has gotten so massive that the Financial Times asked “Are Big Tech bonds crowding out the US Treasury?”
And while the answer is likely, “no”, this chart from the article shows that AI-related debt is going up dramatically and quickly:
https://t.co/eFT7jEnnlg
— Nat Wilson Turner (@natwilsonturner) October 12, 2026
JPMorgan Asset Management’s Michael Cembalest has also created an alarming arrow go up and to the right graph:
https://t.co/BpkiPipJU3
— Nat Wilson Turner (@natwilsonturner) October 12, 2026
Yahoo! Finance is also sounding the alarm:
The total capital raised by hyperscalers, data center special-purpose vehicles, and neo-clouds in the form of investment-grade debt, high-yield debt, and equity capital rose from $172 billion in 2025 to $346 billion thus far in 2026, an increase of more than 100%, per new research from Barclays strategist Venu Krishna on Wednesday.
…
On the debt front, Alphabet (GOOG, GOOGL), Amazon (AMZN), Meta (META), Microsoft (MSFT), and Oracle (ORCL) collectively raised about $159 billion in bonds through early June 2026 — a 47% increase from what these companies issued all of last year.Alphabet, for instance, became the first tech company in decades to issue a 100-year bond, raising $31.51 billion in February across its global bond offering.
https://t.co/rWAKMgjE3l
— Nat Wilson Turner (@natwilsonturner) October 12, 2026
Michael Burry and others have also been alarmed by the amount of off-balance-sheet liability the hyperscalers have accrued. As Axios reported in August, citing Morgan Stanley:
Morgan Stanley looked at filings from the hyperscalers Google, Meta, Microsoft, Oracle and Amazon, as well as the chipmakers Nvidia and Broadcom and broke down their off-balance-sheet commitments.
The hyperscalers have committed to $1.1 trillion in payments for data center leases that haven’t yet begun.
All seven companies have also agreed to buy $1.7 trillion of other stuff — purchase commitments for chips, memory and networking gear.
These purchase agreements have ramped up this year — Google’s commitments totaled $707 billion in the most recent quarter — from $72.5 billion in all of 2025, per the research.
https://t.co/u3hW8iaJPd
— Nat Wilson Turner (@natwilsonturner) October 12, 2026
Those off-balance-sheet obligations are real debt, and it trades. The structure works like this: a special purpose vehicle (SPV), mostly owned by an asset manager, borrows the money, builds the data center and leases it to the tech company. The tech company books the rent as a lease. The bonds sit with the SPV. Prices on those bonds have been sliding.
- Meta, Hyperion (Louisiana): Beignet Investor LLC, 80% owned by Blue Owl funds and 20% by Meta, sold $27bn of 6.581% bonds due 2049 in October 2025. Pimco bought about $18bn of them and BlackRock ETFs more than $3bn. On 28 September the bonds traded at 91 cents on the dollar, a 7.55% yield, about 230 basis points over Treasuries versus 185 at launch, and they hit a record low on 7 October. Meta signed four-year initial leases with options to renew for up to 20 years. It also gave a residual value guarantee of about $28bn: if Meta leaves and the campus is worth less than an agreed amount, Meta covers the shortfall up to that figure. Meta calls a payout “not probable” and records no liability. S&P rated the bonds A+ but warned that substantial credit risk passes back to Meta.
- Meta, El Paso (Texas): Sopaipilla Investor LLC, 80% owned by BlackRock funds and 20% by Meta, sold $12.5bn of 7.534% bonds due 2048 in July, priced 287.5 basis points over Treasuries. Bloomberg called that yield “a level more common in junk bonds” and said demand was “tepid by one standard measure.” Meta’s residual value guarantee on El Paso is about $13bn.
- Microsoft, QTS (Georgia): Microsoft has sold no bonds of its own in two fiscal years but has $329.1bn of data-center leases signed and not yet started. Its landlords do the borrowing. Blackstone’s QTS sold about $3.9bn of five-year bonds in August for a Microsoft-leased Georgia project, at a yield in the low-to-mid 7% range, comparable to single-B junk. Bloomberg’s headline: “Bond Traders Bite at Microsoft-Tied Data Center Junk-Like Yields.” In April a QTS bond refinancing its Fayetteville, Georgia campus, where Microsoft is the tenant, raised $4.6bn.
Not Just the HyperScalers, the Banks Too
Barclays pointed out this week that the banks are following big tech into debt. Per Bloomberg:
Analysts from Barclays Plc estimate the six largest US banks will tap the debt market for about $41 billion in the current quarter, an amount that would be 30% above the fourth-quarter average going back to 2015. In the third quarter, senior debt issuance reached $50 billion, more than double prior-year levels, according to Barclays.
Banks have ramped up borrowing to finance not only the AI buildout, and the hundreds of billions being spent by hyperscalers and tech giants from SpaceX to Oracle Corp., but also to facilitate the increased trading and market activity that has cropped up in tandem with the growing industry…

Year to date, these banks have borrowed $192 billion globally, up some 40% from the same time last year, with the full-year tally estimated at $233 billion, according to the Barclays strategists. For US banks as a whole, they now forecast full-year senior debt issuance of $294 billion, some 25% higher than their initial estimate and up from $240 billion in 2025.
Among the six banks, Goldman Sachs and Morgan Stanley, which have led 2026 issuance, may be the most active borrowers post earnings next week, said Bloomberg Intelligence analyst Arnold Kakuda.
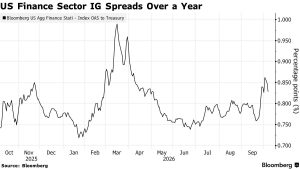
While banks are particularly savvy when it comes to timing borrowing, a recent surge in benchmark borrowing costs may be a deterrent to adding on too much debt. Meanwhile, indications of growing credit concerns around the hyperscalers and other tech borrowers point to increasing unease over the piles of debt feeding the heavy spending on AI.
There’s another set of players in addition to the banks: private credit.
Private Credit Has Piled In
Behind the banks sits private credit: loans made directly by asset managers like Blue Owl, Apollo, Blackstone, Pimco and Brookfield, using money from pension funds, insurers and, increasingly, individual investors in non-traded funds. The loans mostly don’t trade, so their value is whatever the lender says it is. Morgan Stanley estimated in 2025 that data centers would need about $1.5tn of outside financing through 2028, with about $800bn coming from private credit. The Bank of England’s Financial Policy Committee now cites Morgan Stanley’s estimate of about $700bn of data-center spending over 2026-2028 financed by private credit.
Who’s in:
- Blue Owl owns 80% of Meta’s Hyperion campus, put about $3bn of equity into Oracle’s Project Jupiter, and is a partner in the Abilene Stargate site. Reuters reported it struggled to syndicate a $4bn CoreWeave-anchored deal in Lancaster, Pennsylvania.
- Apollo and Blackstone put up $35bn to buy chips for Anthropic, which UBS Asset Management calls the largest private credit deal on record. Blackstone is leading the $18bn junior piece of Broadcom’s new $60bn Anthropic chip package and plans to keep $9bn of it. Apollo is weighing raising its loan to SoftBank’s Vision Fund 2 from $5.4bn to $9bn to help fund SoftBank’s OpenAI commitments.
- Pimco bought about $18bn of the Hyperion bonds and about $10bn of the $14bn of bonds for Oracle’s Michigan site, then sought to sell parts of the Michigan debt.
- Nvidia signed agreements in August with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR to set up financing platforms meant to raise more than $500bn from outside investors for Nvidia’s customers.
Signs of strain:
- Blue Owl again capped withdrawals from two of its private credit funds after investors asked to pull 39% and 17% of their shares, about $4.2bn in all (2 October). Apollo capped a fund after 14.7% of investors asked to exit (22 September). Blackstone’s flagship private credit fund capped redemptions at 5% again (3 September).
- Fitch put the US private credit default rate at a record 6.3% for the year to August.
- SEC staff issued a statement on how funds value private assets on 28 September. Three days later Apollo said it would start pricing its roughly $850bn of credit assets daily.
Perhaps this is why investor demand for tech debt is rapidly declining.
Investor Demand for Tech Debt Takes a Dive
Another Bloomberg piece, titled “AI Debt Spree Hammers Tech Debt as Traders Rush to Reprice Risk.
Highlights:
The pace and sheer scale of the borrowings, combined with unknowns around the technology and rising interest rates, is put growing pressure on the sector. Tech has been among the worst-performing sectors across credit in recent months, leaving investors nursing losses, while average daily trading volumes for tech names in the bond and credit derivatives markets have soared.
In recent days, news of a wave of potential fresh financings from SpaceX and Broadcom, possibly topping $100 billion, sent credit derivatives linked to hyperscalers and chipmakers climbing to prices that suggest traders see a growing risk of a default over the next five years. For Oracle, it’s now above 20%, for SpaceX it’s about 16% — and even Nvidia Corp., the world’s most valuable company, is given a more than 7% risk of default in that time.
…
So-called mega transactions in the tens of billions of dollars used to be few and far between and syndicate banks would spend months telegraphing the deals ahead of launch, plus most of the huge deals were earmarked for mergers and acquisitions. This year, there have been nine US high-grade deals that are $25 billion or above in size, the most ever, most of them in tech.The US high-yield market, meanwhile, is poised for one of its busiest year on record. And while debt markets have absorbed the record supply relatively well, investors are starting to demand higher compensation to lend to the sector, particularly as financing needs expand beyond the so-called hyperscalers into chip financing, data centers, and other structures, according to Steven Kohlenstein, fixed-income portfolio manager at T. Rowe Price.
https://t.co/owUnJVcm2G
— Nat Wilson Turner (@natwilsonturner) October 12, 2026
For now the issue is less about actual deterioration in credit quality than about market saturation. Most of these big borrowers are profitable, with steady cash flow and earnings momentum. And their weaker performance hasn’t spilled over into the broader market, which has held up relatively well.
These borrowers are also tapping as many corners of demand as they can, borrowing in global markets and exploring various debt structures to help mitigate risks. But even so, the crush of debt in such a relatively short span of time gives investors at least some bargaining power to demand more compensation for taking on the debt. And there are unknowns about the AI rollout, the potential payoff and the risks around the technology, all of which could upend valuations.
Among expected borrowings that have recently come to light, Broadcom is sketching out plans for its next blockbuster deal just days after it launched a $60 billion debt financing to help fund Anthropic PBC’s artificial intelligence buildout, Bloomberg reported Wednesday.
Broadcom’s five-year CDS widened by 3 basis points to a record 136 basis points on Thursday, according to ICE Data Services.
It’s quite a party, although there may be the proverbial poop in the punchbowl, in the form of delayed data centers.
Who’s Holding the Bag for Those Data Centers?
For every data center delayed by “force majeure” and otherwise, there is a counterparty holding the bag. Here’s what I can put together about who owes what for some of the bigger projects:
| Project | Debt | Banks | Status |
|---|---|---|---|
| Project Jupiter, N.M. Oracle tenant; Blue Owl/Stack |
$18bn | About 20 banks; SMBC, BNP Paribas, Goldman, MUFG agents | Quoted at 89-91 cents; Santander, Jefferies holding more than planned (18 Sep). Oracle force majeure notice 24 Sep; Morgan Stanley: weighs on data-center debt |
| Vantage, Texas + Wisconsin Oracle tenant |
$38bn | JPMorgan, MUFG lead; Wells Fargo, BNP, Goldman, SMBC, SocGen | Months to sell down; some lenders still offloading (Apr) |
| Hubbard, Texas Anthropic tenant; Google backstop |
$15bn | Morgan Stanley lead | Banks seeking to offload (FT, Aug) |
| AI data-center loans, various | — | JPMorgan, Morgan Stanley, SMBC, MUFG | Explored loan sales and significant risk transfers (FT, May) |
The scary part is who is ultimately on the hook to pay for these data centers. Sometimes that’s the weakest links in the chain.
Who’s On the Hook and For What?
The chipmakers and cloud giants are also guaranteeing their customers’ debt. When a lab like OpenAI or Anthropic, or a small cloud company like Fluidstack, can’t borrow on its own credit, a bigger company promises to cover the rent if the customer stops paying. The lenders are really lending against that promise. None of it shows up as debt on the guarantor’s balance sheet.
- Nvidia and OpenAI: In an 8-K filed 17 August, Nvidia agreed to guarantee up to $105bn of the value of leases OpenAI is signing for about 4.25 gigawatts at SB Energy’s campus in Pike County, Ohio. If OpenAI goes insolvent or stops paying, Nvidia pays the gap between the guaranteed lease value and whatever the landlord recovers by re-leasing or selling the site. The guarantee runs up to 20 years, and Nvidia has an option to back about 3.8 more gigawatts. The Wall Street Journal reported the talks at $250bn in July. Nvidia’s latest 10-Q puts its total maximum guarantee exposure at $108.5bn, including $3.5bn on data-center leases for smaller AI cloud companies, which it took on in exchange for warrants in those companies.
- Google: Alphabet’s 10-Q shows backstops of other companies’ data-center leases rose to $43.8bn at the end of June, from $16.9bn six months earlier, with terms of up to 15 years. It has agreed to about $24.1bn more. Google accounts for them as credit derivatives. Several of the disclosed deals back Fluidstack, a small AI cloud company, at sites owned by former bitcoin miners. Google backstopped $1.8bn of Fluidstack’s leases at TeraWulf’s Lake Mariner site, $1.3bn at TeraWulf’s Abernathy, Texas, site and $1.73bn at Cipher Mining’s Barber Lake, Texas, site, taking warrants in the miners in some of the deals. Google also backstops rent and power at Anthropic’s Hubbard, Texas, campus, where banks are lining up $15bn of debt. Bloomberg reported the backstop was needed because Anthropic has no credit rating.
- Amazon: The Financial Times reported on 2 October that Amazon is in talks to move about $8bn of Nvidia Grace Blackwell chips into an SPV that would raise debt and equity from outside investors, then lease the chips back. The chips would stay in AWS data centers. Investors expect the debt to get an investment-grade rating tied to Amazon’s own AA rating. Amazon declined to comment.
Unfortunately, there’s one other problem: free cash flow, or the lack thereof.
Free Cash Flow, My Kingdom for Free Cash Flow
Why borrow at all? These are some of the most profitable companies in the world. But the data-center bill now eats up nearly all the cash the businesses throw off. Goldman Sachs estimates the big hyperscalers will spend about $750bn on capex in 2026, against about $778bn of operating cash flow. That leaves about $28bn to spare, and Goldman expects debt to pay for about a third of capex this year.
- Amazon: Free cash flow over the trailing twelve months went negative, to -$7.6bn at the end of June, from +$18.2bn a year earlier and $25.9bn in early 2025. Capex over the same period hit $169bn, up $66bn. So Amazon borrowed: $82.4bn of new debt in the first half alone, nearly doubling its long-term debt to $133bn from $68.8bn at the end of 2025. Its 10-Q says it expects “additional financing activities in 2026,” and it sold £4.25bn of bonds in September.
- Oracle: Free cash flow was -$5.4bn in the quarter to August, after -$23.7bn for the fiscal year that ended in May. Capex was $28.5bn in the quarter, up from $8.5bn a year earlier. Interest expense rose to $1.43bn from $923m. To cover the gap Oracle sold $19.9bn of stock through an at-the-market program and took $11.4bn of prepayments from customers. S&P cut Oracle to BBB- in July, one notch above junk, and forecasts a free cash flow deficit of nearly $42bn for this fiscal year.
- Microsoft is the exception on paper. It brought in $182.9bn of operating cash in its fiscal year to June and spent $115.9bn on property and equipment, and it hasn’t sold a bond in two years. But those capex figures leave out its finance leases, which rose to $66.6bn from $46.2bn, and the $329.1bn of data-center leases it has signed that haven’t started yet.
Fun party, it would be a shame if someone took away the punchbowl.


 By